
When Should Associations Submit a CGL Claim?
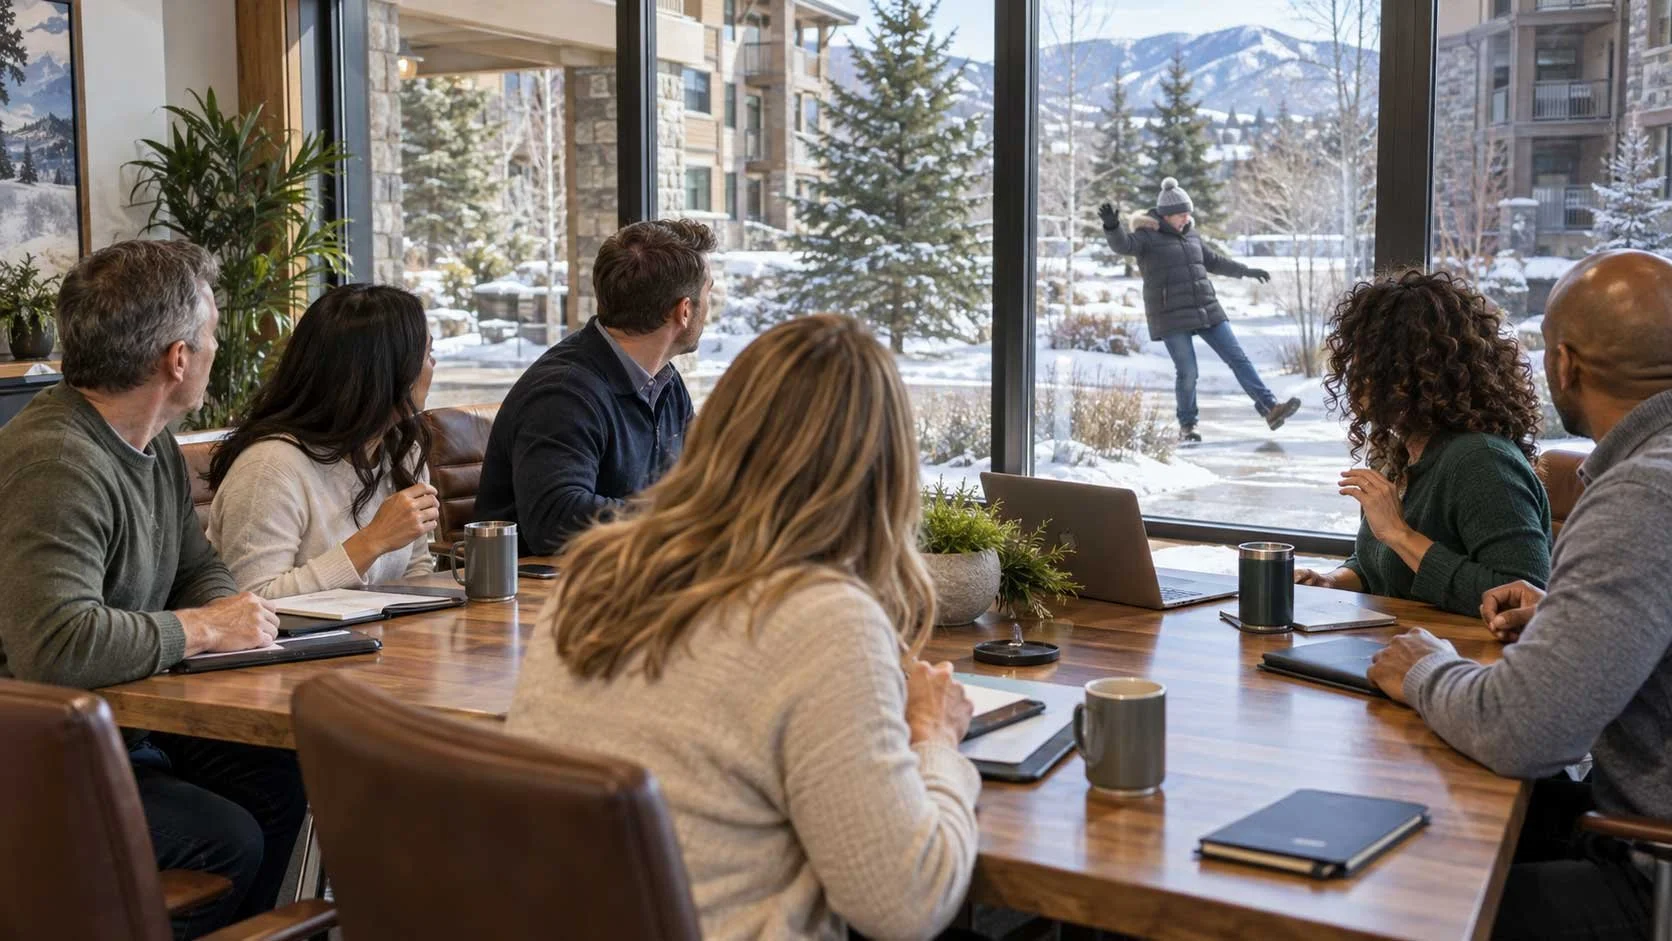
When an HOA receives a demand or lawsuit, one of the first questions should be whether to submit it to the Association’s commercial general liability (CGL) insurer. Coverage A generally applies to accidental bodily injury and property damage caused by an occurrence — such as slip-and-falls, water damage, or damage to an owner’s property. But CGL policies may also provide Coverage B for less obvious claims involving wrongful entry, invasion of private occupancy, defamation, disparagement, or invasion of privacy.
The key is not simply what the claimant labels the dispute. Under Colorado law, an insurer’s duty to defend can arise when the alleged facts satisfy the elements of a covered claim, even if the complaint uses a different label. At the same time, CGL policies contain important exclusions, including for intentional damage, pollution, employment claims, automobile liability, and certain defective-work claims. Associations therefore should look at the specific factual allegations and policy language before assuming a claim is either covered or excluded.
Not every minor dispute needs to become an insurance claim. There is a practical downside to submitting claims: they become part of the Association’s loss history and may affect renewal underwriting, premiums, deductibles, or available coverage. That does not mean legitimate claims should be withheld simply to protect the Association’s claims record. The better approach is proportionality. For potentially significant or uncertain claims, Associations should evaluate coverage early and preserve their insurance rights rather than discovering later that a claim should have been tendered months earlier.
If you would like help evaluating the pros and cons of submitting a CGL insurance claim on behalf of the association, the experienced lawyers at Moeller Graf are available to assist. This information should be viewed as informational and not direct legal advice.